
Sunday, February 20, 2011

What is a Commercial Signal Failure
This is in response to a special request from my pal the Turd who has asked me if I would take a bit of time to explain the titled term. It dovetails nicely with my comments on the impact of margin requirement hikes by the exchanges.
Let me begin this explanation by saying that these events are relatively rare. Over the course of my career I can probably count the number of times that I have seen them occur on both hands. That is not to say that there have not been more, but in the particular markets that I actively trade, they are infrequent. However, when they do occur, the resultant price moves are spectacular; i.e. if you happen to be on the correct side. If you are not - well - you are probably no longer reading posts or having anything else to do with commodity futures markets and are gainfully employed elsewhere having had your net worth reduced by multiples.
Let's also take a Commercial Signal Failure (hereafter referred to as CSF) in a bull market. I have seen one occur in the hog market twice in my career and those were strong bear moves that resulted from chicken import bans and H1N1 outbreaks but for the most part, these things happen in a bull market.
Here is the scenario - a market begins a trending move higher. Speculators are on the long side driving the price upward with the Commercials (producers, processors, etc.) instituting hedges for risk management and selling into the speculator buying. This is all healthy and normal for the Commercials are using the futures markets for the reason that they came into being - they are locking in profit margins and eliminating price risk by transferring that risk to a speculator who is willing to assume the risk in the hopes of making money as prices move higher. It is also the reason that all bull markets that have any lasting power will always see a rise in open interest as price moves higher. Commercials are employing scale up selling programs to lock in successively higher sales prices for their production. This can be abused as it has been in gold and silver but that is another story that we all know too well.
As the price continues to move higher, commercials will attempt to take advantage of the speculative buying and will sell more and more of their expected future production. In other words, the size of their short position continues to grow as they cover their risk management needs. Now in order to maintain this short position, they are required like anyone else who has a position in the futures market to post margin. Bona fide hedgers have a distinct advantage in this however since the margin requirements for a hedger are less than that required by a speculator to post. In other words, they can control more contracts for the same amount of money than can a speculator.
The reason for this is because supposedly there is less risk for a hedger from a financial standpoint because they actually produce the commodity that they are hedging. If they lose money on the hedge, the short position, that is offset by the corresponding rise in the physical commodity. This conceivably puts them on a sounder financial footing than a speculator who is putting risk money up without having access to the underlying physical.
So far the scenario is developing like it does in every single bull market - the price rises, the speculators are on the long side, the commercials are on the short side, and the total open interest (number of contracts open) is rising. Obviously the speculators are now showing good open or paper profits on their long positions with the commercials showing paper losses on their open short positions. As price continues to rise, these commercials will also be required to post additional margin money to bring their positions back to what is called the maintenance level. The higher the price rises, the more money they must expend to meet all the clearinghouse requirements. That however is generally not a problem since these things are accounted for in their risk management programs and they have access to lines of credit which will allow them to make good on these financial requirements.
A problem develops for them however when there is an event, an occurence or development of some sort which drastically changes the supply/demand picture overnight. For example, a hard freeze could crush the Florida orange crop; a severe drought or flood could wipe out a substantial portion of a major agricultural crop, a livestock disease could surface in a major producing nation, a blight could strike the cocoa producing areas of West Africa, it could nearly anything. Whatever the event, it triggers an immediate shift in that fundamental supply and demand equation that results in a huge imbalance between demand and supply in favor of the speculators. In other words, supply has been severely impacted and sharply reduced or demand has shot up suddenly and is now grossly overwhelming supply. The result - prices spike rapidly upward and begin to accelerate higher as the market must now come to terms with the new and greatly alterated supply/demand equilibrium.
Commercials, who now find themselves on the short side of the market with a substantial position are suddenly caught flatfooted as panic buying grips the market and all offers to sell instantly disappear. The result is a massive air pocket above the market with a huge imbalance of buyers and sellers. Simply put - there are no sellers, anywhere. Everyone wants to buy and they have no one to buy from. What happens? Price must rise higher and higher until it reaches a level where the sellers, those who actually have the product, feel comfortable letting some of their supply go.
Some might say, well, what is the big deal for those commercials? After all, they have the product and while they are losing money on their short hedges, they are making it back on the physical side of thing because they actually produce the commodity. That is true and in a normal bull market, that is exactly what happens, but in a situation as above, where the event has come out of nowhere and was not anticipated and is of such magnitude that it severely throws the balance between supply/demand grossly out of balance, even these commercials are impacted.
Why is this? The answer goes back to the margin requirements. In a rising market, commercial hedgers with short positions are constantly losing money on those hedges and are required to post additional sums of money to keep current and maintain those short positions. As stated previously, to do this they draw from their own reserves which are set aside for risk management purposes. In addition they have lines of credit from various lenders who loan them the money for such purposes. But when an event alters the market dynamics to such an extent that price begins to gap higher and accelerates upward, their lines of credit are no longer sufficient to cover the paper losses on their open short positions.
In other words, they run into the exact same position as a speculator who has a market moving against him and no longer has the financial resources to maintain his margin deposit at the proper level. They are forced to get out of their positions because they have run out of money to maintain them. Unable to get any further credit and having drawn down their own reserves, they are now defenseless and must buy back the existing shorts to prevent the financial ruin of their firm.
They too now enter the buying frenzy only this time, their ability to get out of their shorts determines whether or not their firm will survive. They will hit every single available offer to sell that might appear because their very life depends on getting out. They do not care what the cost is - they must get out.
The implications are obvious - price will rise and rise and rise until every last one of those losing short positions have been cleaned out to the level that enables that firm to survive. As to how high that market will then go, it is anyone's guess. Quite frankly no one knows. It will stop at some point but by then the damage to the shorts is staggering.
Over the years I have seen entire firms go down when an event such as this transpired.
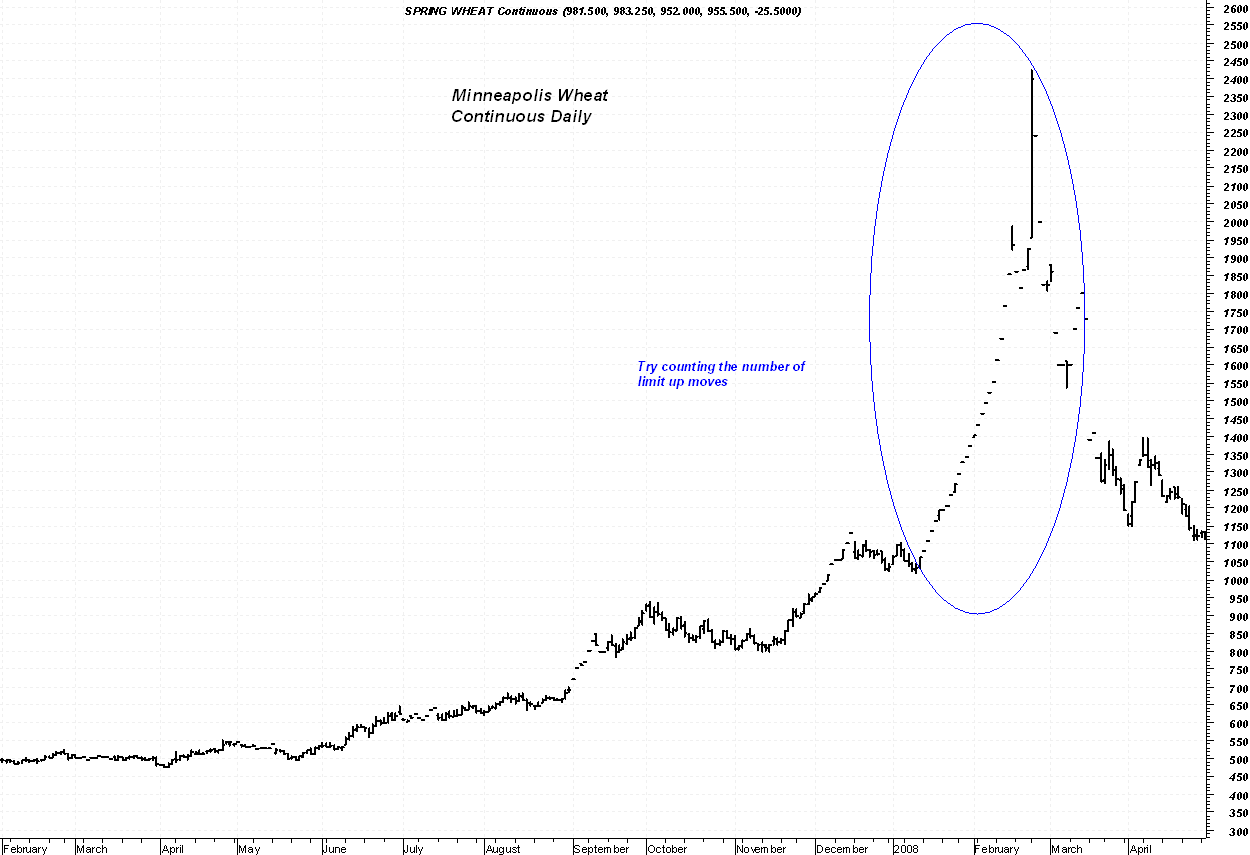
Here are a few charts detailing the results of a CSF. The first is in Live Cattle and the second is in Minneapolis Wheat.
With Live Cattle, the "black swan" event was the discovery of a cow in Canada back in 2003 that came down with "mad cow" disease resulting in the US authorities closing the border to all shipments of Canadian beef and live cattle. The result was an immediate shift in the supply/demand balance with US supply sharply curtailed and unable to meet the then existing demand. Price shot sharply higher moving limit up 8 days in a row, 5 of those days being gaps in which the market basically shut down because there was no one to sell.
I can still remember the cries and pleas from the commercials who were members of the CME for the exchange to do something because they could not get out and were being ruined.

The Minneapolis Wheat market, back in the winter of 2008, was roiled by a perfect storm of developments that seemed to come together all at once. Horrific crop weather, soaring demand, export bans from wheat growing countries, it just all hit at once. The result was the most spectacular Commercial Signal Failure that I have ever seen. Price soared from an already expensive $10.00/bushel to nearly $24.50 for a single bushel of this wheat! The market literally did not trade for days on end as it opened at limit bid day after day with absolutely no one to sell. There were more than a few firms who were destroyed as a result of their short hedges in this market.

I do want to point out something about these CSF's. Note that once they run their course, the market generally collapses and gives back a very large percentage of its overall gains. That is because once all the Commercials have finished buying back their bleeding short positions, there is no one left to buy and prices now come tumbling back to earth. In some cases, all the price rise is erased; in other cases a substantial portion are given back but the market then finds a footing at a new and higher price level.
As with any market, the potential always exists for such a development especially when there exists a very large short contingent in a market that has already seen a decent price rise. Any further exacerbations of the supply/demand balance can trigger one of these events. If one does happen in silver, trust me on this one, you will not have to ask the question: "Gee I wonder if we are seeing a Commercial Signal Failure in Silver". You will know it.
Let me begin this explanation by saying that these events are relatively rare. Over the course of my career I can probably count the number of times that I have seen them occur on both hands. That is not to say that there have not been more, but in the particular markets that I actively trade, they are infrequent. However, when they do occur, the resultant price moves are spectacular; i.e. if you happen to be on the correct side. If you are not - well - you are probably no longer reading posts or having anything else to do with commodity futures markets and are gainfully employed elsewhere having had your net worth reduced by multiples.
Let's also take a Commercial Signal Failure (hereafter referred to as CSF) in a bull market. I have seen one occur in the hog market twice in my career and those were strong bear moves that resulted from chicken import bans and H1N1 outbreaks but for the most part, these things happen in a bull market.
Here is the scenario - a market begins a trending move higher. Speculators are on the long side driving the price upward with the Commercials (producers, processors, etc.) instituting hedges for risk management and selling into the speculator buying. This is all healthy and normal for the Commercials are using the futures markets for the reason that they came into being - they are locking in profit margins and eliminating price risk by transferring that risk to a speculator who is willing to assume the risk in the hopes of making money as prices move higher. It is also the reason that all bull markets that have any lasting power will always see a rise in open interest as price moves higher. Commercials are employing scale up selling programs to lock in successively higher sales prices for their production. This can be abused as it has been in gold and silver but that is another story that we all know too well.
As the price continues to move higher, commercials will attempt to take advantage of the speculative buying and will sell more and more of their expected future production. In other words, the size of their short position continues to grow as they cover their risk management needs. Now in order to maintain this short position, they are required like anyone else who has a position in the futures market to post margin. Bona fide hedgers have a distinct advantage in this however since the margin requirements for a hedger are less than that required by a speculator to post. In other words, they can control more contracts for the same amount of money than can a speculator.
The reason for this is because supposedly there is less risk for a hedger from a financial standpoint because they actually produce the commodity that they are hedging. If they lose money on the hedge, the short position, that is offset by the corresponding rise in the physical commodity. This conceivably puts them on a sounder financial footing than a speculator who is putting risk money up without having access to the underlying physical.
So far the scenario is developing like it does in every single bull market - the price rises, the speculators are on the long side, the commercials are on the short side, and the total open interest (number of contracts open) is rising. Obviously the speculators are now showing good open or paper profits on their long positions with the commercials showing paper losses on their open short positions. As price continues to rise, these commercials will also be required to post additional margin money to bring their positions back to what is called the maintenance level. The higher the price rises, the more money they must expend to meet all the clearinghouse requirements. That however is generally not a problem since these things are accounted for in their risk management programs and they have access to lines of credit which will allow them to make good on these financial requirements.
A problem develops for them however when there is an event, an occurence or development of some sort which drastically changes the supply/demand picture overnight. For example, a hard freeze could crush the Florida orange crop; a severe drought or flood could wipe out a substantial portion of a major agricultural crop, a livestock disease could surface in a major producing nation, a blight could strike the cocoa producing areas of West Africa, it could nearly anything. Whatever the event, it triggers an immediate shift in that fundamental supply and demand equation that results in a huge imbalance between demand and supply in favor of the speculators. In other words, supply has been severely impacted and sharply reduced or demand has shot up suddenly and is now grossly overwhelming supply. The result - prices spike rapidly upward and begin to accelerate higher as the market must now come to terms with the new and greatly alterated supply/demand equilibrium.
Commercials, who now find themselves on the short side of the market with a substantial position are suddenly caught flatfooted as panic buying grips the market and all offers to sell instantly disappear. The result is a massive air pocket above the market with a huge imbalance of buyers and sellers. Simply put - there are no sellers, anywhere. Everyone wants to buy and they have no one to buy from. What happens? Price must rise higher and higher until it reaches a level where the sellers, those who actually have the product, feel comfortable letting some of their supply go.
Some might say, well, what is the big deal for those commercials? After all, they have the product and while they are losing money on their short hedges, they are making it back on the physical side of thing because they actually produce the commodity. That is true and in a normal bull market, that is exactly what happens, but in a situation as above, where the event has come out of nowhere and was not anticipated and is of such magnitude that it severely throws the balance between supply/demand grossly out of balance, even these commercials are impacted.
Why is this? The answer goes back to the margin requirements. In a rising market, commercial hedgers with short positions are constantly losing money on those hedges and are required to post additional sums of money to keep current and maintain those short positions. As stated previously, to do this they draw from their own reserves which are set aside for risk management purposes. In addition they have lines of credit from various lenders who loan them the money for such purposes. But when an event alters the market dynamics to such an extent that price begins to gap higher and accelerates upward, their lines of credit are no longer sufficient to cover the paper losses on their open short positions.
In other words, they run into the exact same position as a speculator who has a market moving against him and no longer has the financial resources to maintain his margin deposit at the proper level. They are forced to get out of their positions because they have run out of money to maintain them. Unable to get any further credit and having drawn down their own reserves, they are now defenseless and must buy back the existing shorts to prevent the financial ruin of their firm.
They too now enter the buying frenzy only this time, their ability to get out of their shorts determines whether or not their firm will survive. They will hit every single available offer to sell that might appear because their very life depends on getting out. They do not care what the cost is - they must get out.
The implications are obvious - price will rise and rise and rise until every last one of those losing short positions have been cleaned out to the level that enables that firm to survive. As to how high that market will then go, it is anyone's guess. Quite frankly no one knows. It will stop at some point but by then the damage to the shorts is staggering.
Over the years I have seen entire firms go down when an event such as this transpired.
Here are a few charts detailing the results of a CSF. The first is in Live Cattle and the second is in Minneapolis Wheat.
With Live Cattle, the "black swan" event was the discovery of a cow in Canada back in 2003 that came down with "mad cow" disease resulting in the US authorities closing the border to all shipments of Canadian beef and live cattle. The result was an immediate shift in the supply/demand balance with US supply sharply curtailed and unable to meet the then existing demand. Price shot sharply higher moving limit up 8 days in a row, 5 of those days being gaps in which the market basically shut down because there was no one to sell.
I can still remember the cries and pleas from the commercials who were members of the CME for the exchange to do something because they could not get out and were being ruined.

The Minneapolis Wheat market, back in the winter of 2008, was roiled by a perfect storm of developments that seemed to come together all at once. Horrific crop weather, soaring demand, export bans from wheat growing countries, it just all hit at once. The result was the most spectacular Commercial Signal Failure that I have ever seen. Price soared from an already expensive $10.00/bushel to nearly $24.50 for a single bushel of this wheat! The market literally did not trade for days on end as it opened at limit bid day after day with absolutely no one to sell. There were more than a few firms who were destroyed as a result of their short hedges in this market.
I do want to point out something about these CSF's. Note that once they run their course, the market generally collapses and gives back a very large percentage of its overall gains. That is because once all the Commercials have finished buying back their bleeding short positions, there is no one left to buy and prices now come tumbling back to earth. In some cases, all the price rise is erased; in other cases a substantial portion are given back but the market then finds a footing at a new and higher price level.
As with any market, the potential always exists for such a development especially when there exists a very large short contingent in a market that has already seen a decent price rise. Any further exacerbations of the supply/demand balance can trigger one of these events. If one does happen in silver, trust me on this one, you will not have to ask the question: "Gee I wonder if we are seeing a Commercial Signal Failure in Silver". You will know it.
Saturday, February 19, 2011
Trader Dan on King World News Weekly Metals Wrap
To listen to my radio interview with Eric King of King World News on the Weekly Metals Wrap, please click on the following link:
You can also hear Bill Haynes, from CMI Gold & Silver whose views on the physical product market are always informative and insightful.
http://www.kingworldnews.com/kingworldnews/Broadcast/Entries/2011/2/19_KWN_Weekly_Metals_Wrap.html
You can also hear Bill Haynes, from CMI Gold & Silver whose views on the physical product market are always informative and insightful.
http://www.kingworldnews.com/kingworldnews/Broadcast/Entries/2011/2/19_KWN_Weekly_Metals_Wrap.html
Silver Margin Hikes
I wish to clear up a misconception floating around that the CME has hiked margin requirements on the main silver contract. It has not. Margins were raised on silver intramarket spreads, not the main 5,000 ounce silver contract.
Margin requirments for the full sized, 5,000 ounce contract remain the same as last month (Jan 20) when they were raised to $11,138 from $10,463 for initial margin.
The previous hike in margin rates for silver occured last year (Dec 16, 2010) when they were raised to $10,463 from $9,788.
Prior to that, margin rates on these full sized silver contracts were raised Nov 16, 2010 when the initial margin requirement was raised to $9,788 from $8,775.
I will keep the community updated on any subsequent margin hikes in silver or in gold.
Some thoughts on Analysts and the Silver market
I have been reading with some amusement the comments of some who seem as if their sole raison d’etre is to provide a perpetual example of folly masquerading under the supposed guise of wisdom.
Let me first begin by saying that as a trader of more than two decades’ experience, there have been, and I am sure, will be, times when I have been wrong about a market. I feel no shame in admitting that – why should I, as I am a mere mortal and am not infallible. To give a recent example – I have been a bear on the US US
I might add here that I had also been wrong about the bond market for some time and was of the opinion that a falling Dollar would result in a falling bond market. That too was not the case during the credit crisis of 2008. I learned a good lesson about all that back then.
I still have my doubts about the veracity of this move higher in US equities or of its ability to endure but the fact is that the stock market is moving higher, regardless of what I think about it.
Now, as a trader I can do one of three things with this.
One – I can continue to stubbornly insist that the stock market should not be going up and take out a huge short position and continue until my trading account is no more, declaring that the US - satisfaction of telling myself and others: “SEE, I was right all along. I told you so”. Result – I am broke and busted but feel proud and smug.
Two – I can do nothing and stay flat because while I see the market moving higher am greatly suspect of its lasting power. I will not make any money following this course of action but neither will I get hurt financially either.
Three – I can see the trend and while I greatly suspect its lasting power, can take a long position and attempt to ride that trend higher until such time I see it nearing an end. This course of action, while fraught with peril because of my own views of the market, will make me money as a trader if I employ sound money management techniques and use wisdom and do not get careless or complacent.
Here is the lesson in all this, a lesson I might add, learned the painful way through many years experience. THE MARKETS DO NOT CARE ONE B IT AB OUT OUR OPINION.
The sooner one learns this lesson, the better a trader/investor they will become.
I remember earlier in the past decade reading the reports from a rather well known and respected analyst who was consistently bearish on the copper market. B ack in 2006, when copper was trading closer to $2.00, having rallied up from down near $1.40 - $1.50, he kept producing studies adamantly denying any reports suggesting that there was a tightness in the copper supply based on real fundamental supply/demand statistics. He cited reasons such as hedge funds artificially distorting the supply by taking huge sums of copper off the market and storing it in warehouses thereby creating the drawdown in stocks at the LME and in Shanghai that were being registered. He stated that copper was therefore overpriced and was primed for a fall.
This he continued doing while copper rose towards $2.50 - $2.60 pound. He was still bearish while copper went on to hit $3.00. “Still overpriced”; “No real shortage”; “Supply is being artificially reduced – the copper is still there just not in the public warehouses”, etc. all the while the price of copper kept rising. B efore it all ended, copper had moved up to over $4.00 in May 2006 before it finally sold off. It then retreated all the way down to $2.40 before it turned around and went back up again reaching nearly $4.30 in 2008 before it crashed alongside the rest of the commodity complex when the credit crisis erupted.
Maybe this analyst was right; maybe he was wrong; maybe hedge funds were indeed taking copper out of storage in public warehouses and stashing it into private warehouses. W ho knows and who really cares at this point? Here is the point in all this recapping. One could have followed the three options just cited.
Option one: “W ell Mr. respected analyst says that copper is overpriced and should not be moving higher. Therefore I will listen to Mr. respected analyst and take a short position”. W hat would the result have been for the average trader/investor? Answer – the average trader/investor would have lost the entire amount invested on a short copper position if not more due to the leverage effect. Question – was this a good course of action? Answer – obviously it was foolhardy.
Option two: “Mr. respected analyst says that copper is overpriced and should not be moving higher. He is probably right because he knows more than me but I see the price chart is moving higher and therefore I will do nothing because he must be smarter than me and I must be wrong”. Question – how would that have worked out? Answer – no harm done but neither did the average trader/investor make a single dime. He is no richer or no poorer for his choice and is as well off as he was before. He has however lost a very good opportunity.
Option three: “Mr. respected analyst says that copper is overpriced and should not be moving higher. The price chart however tells me that the market does not care one whit about what Mr. respected analyst thinks because IT IS MOVING HIGHER”. I will therefore take out a long position in copper because I believe that the combined opinions of ALL MARKET PLAYERS is outweighing the opinion of one Mr. respected analyst. Question – how did this choice work out? Answer – the average trader/investor made money and profited from his action. He has increased his wealth and has used a market trend to his advantage.
Let’s now take this a bit further and run it back to silver. W e have the same persistently negative analysts who continue to assert that there is no shortage of silver and that silver is overpriced. Maybe they are wrong; maybe they are right. I personally happen to believe that they are wrong but even at that, who am I and why does what I think about this even matter. The key is that the COMB INED OPINIONS OF ALL PLAYERS that trade in the silver market presently believe that there is a shortage of silver. How do I know this? Simple – the price chart tells me so. W hich way is it going, higher or lower? If the combined opinion of the players in the silver market believed that there was more than enough supply around, more so than current demand supported, the price would not be going higher; it would be going lower.
Not only that, but the backwardation type price structure on the silver board is also saying with a clear and loud voice: “Silver demand is currently extremely strong – so strong that buyers are willing to pay up to obtain the metal right now rather than wait for it”.
Now, we have come full circle and are back to facing the same three choices that I have listed earlier in this commentary.
Option one – the trader/investor listens to the persistently negative analysts who tell him there is no shortage, takes out a short position expecting price to be obedient to their assertions and move lower, only to get run over and left for dead on the trading floor with huge paper losses. He not only does not make a dime, he loses all the money he bet against the rise in silver.
Option two – the trader/investor listens to the persistently negative analysts who tell him there is no shortage but he sees price moving higher and doubts his own judgment. Therefore he does nothing. He makes no money; he loses no money either but then kicks himself for following their opinion and second guessing himself.
Option three – the trader/investor listens to the persistently negative analysts who tell him there is no shortage of silver but he sees the price chart and then comes to the conclusion “ the market is telling me in no uncertain terms that it does not agree with the assertions of the persistently negative analysts because its price chart is telling me so. I will therefore trust my own judgment and take a long position in silver. Question – how did the average trader/investor who followed this course of action fare thus far? Answer – it depends on when they instituted their long positions but let’s just assume that they went long when silver closed above the $30 level and held that tough resistance level refusing to break lower. So far, so good. Now, by employing proper money management techniques, they will be able to lock in a healthy profit if they are a trader or at the very least will have managed a return or gain on the silver bullion they might have purchased.
Here is the final point in this. I have been around this industry for a very long time. Over that time I have seen countless “analysts” come and go. I have also seen some traders who have survived and thrived over that same period. Here is a vital and important distinction that needs to be kept in mind.
Analysts get paid to “analyze” and give opinions on markets. They make money whether their opinion is right or wrong. In that sense they are no different than the TV weatherman. He gets paid to produce a forecast. Sometimes he gets it right; sometimes he gets it wrong but regardless he gets paid. He suffers no consequence for failure. However, those who rely on his forecast and make business plans based on those forecasts may suffer terribly if they act on his forecast.
Take the example of a guy running a concrete company who plans a big pour for a certain day because the weatherman has given his forecast for no rain in sight. The big day comes, the contractor spends thousands of dollars on material and pours only to have a downpour wash it out. The Result – the weatherman goes on TV the next day, issues another forecast and collects his paycheck at the end of the week. He has no accountability or suffers any consequence whatsoever. The unfortunate concrete contractor, who put his faith in the weather forecast, is entirely a different matter. He has lost his thousands and suffered immense pain as a result. Life goes on for the weatherman but the concrete contractor might possibly have been ruined.
Analysts are the same – they can issue opinions all day long and suffer not the least bit of consequence for their failure. However, those who listen to them and make decisions based on those opinions can suffer immense harm. Life goes on for the analyst, no matter how often he is utterly and completely wrong; life can be extremely difficult however for those who took their guidance from him.
Analysts therefore make their living OFF of the market – not IN the market. This is a vital distinction.
Traders on the other hand, make their living IN the market. If we are wrong, we suffer the consequences of our actions. If we are right, we enjoy the reward. If we are wrong, we are forced by the nature of the business to QUICKLY realize and ADM IT we were wrong. B y doing so, we survive and even prosper. Failure to admit when one has erred is not only stupid and foolish, it is ruinous.
Analysts on the other hand generally cannot make a living trading a market. The reason is because many of the ones that I have seen over the decades have had one huge failing that hinders them from ever becoming successful as a trader – their EGO prevents them from admitting error.
Remember this well the next time you read an opinion by an “analyst”.
Good traders are confident but are also humble. If they survive long enough it is because the markets have humbled them and they have learned to respect it above all others. That is why as a trader we let the markets tell us what the COLLECTIVE OPINION of the market players are at any given time. That opinion is always right, even it may happen to be “wrong” in our own minds. Learn to respect only THIS OPINION and you will be successful. Learn to ignore those whose opinion contradicts this COLLECTIVE OPINION, and you will thrive.
The goal in trading is not to be “right” but to make money. Everything else is noise.
Friday, February 18, 2011
Gold Commitment of Traders
Good action here. Lots of spec interest coming from the Managed Money side of the equation whose buying is now driving this market higher.
As you can see on the chart, they have ramped up their net long holdings but even at that remain rather lightly invested in this market, even at current price levels seeing that they are still well off their recent peak holdings.
Swap Dealers and Commercials are once again plying their craft of "Sell, Sell, Sell".
The other large reportables are steadily drawing down their net long holdings and are also at a relatively low level of exposure to the long side compared to the recent past.
The general public, the small specs, are showing some interest in the long side again.

Silver Commitment of Traders
Things are back to business as usual in the Comex silver market with the Managed Money camp eager to buy in on the long side while the Commercials and Swap Dealers generally take the other side of the trade.
Silver has rallied another $2.18 since Tuesday's close which is no mean feat. Short positions in this market are deeply hemorrhaging since that cut off day which makes it all the more remarkable that thus far we are not seeing a reduction in total open interest. That means that the shorts are not being squeezed out yet although yesterday's and today's action has all the hallmarks of a significant short being squeezed out of this market.
There are still some fresh sellers however who keep coming in. Someone on the short side has some amazingly deep pockets to deal with this kind of onslaught and continue piling on more positions.
On the other hand, Managed Money is getting aggressive with this market and because of its small size, they have considerable firepower at their disposal which allows them to run this market very hard to the upside.
The general public is sleeping right now and must have missed this move. They are well down from their recent peak of nearly 20,000 net longs. That I take as a further positive sign.

Reposting the 4 hour silver Chart
I want to thank Charlie for letting me know that I had forgotten to refresh the comments on the 4 hour chart from the other day.
Here is a new, improved version!

Below is a weekly chart of silver employing the Directional Movement Indicator, which is a favorite of mine for determining whether or not a market is in a trending fashion or is just chopping or consolidating.

The line in black, the ADX, will rise if a market is trending. It can be a bit confusing but this line will actually rise if a market is moving lower also, as long as it is a trending move lower.
Generally speaking, when the ADX line turns down, the trend has been interrupted and longs or shorts will want to close out positions at that point and then wait to see what is going to happen next.
By noting the directional lines, the blue and the red, one can then see in which direction the market is pushing.
If the market is moving upward and the trend is higher, both the positive directional movement line and the ADX will be rising in unison. At that time, the negative directional movement line, the red line, will be moving down.
If a market is in a distinct downtrend, the red line will be rising along side of the ADX or black line with the positive directional movement line (the blue line) moving lower.
When the market is not trending, the ADX will be moving lower while one of the directional movement lines will be rising and the other falling depending on where the short term direction is leading.
What looks very promising on this chart is that it is a weekly chart and the ADX has resumed its upward turn which is suggesting a new leg higher as the market is back to trending, in this case, picking up where it left off a few weeks back when the market topped.
Keep an eye on the blue line. Ideally we want to see it surpass the peak from the previous high in price.
There will be more on this as time progresses and we get a chance to see how things play out.
Subscribe to:
Posts (Atom)